
Uber Pro Card
- Rating
- 4.9
- Downloads
- 1.00M
- Content Rating
- Everyone
Uber Pro Card - Screenshots
Pros
- No monthly fee for standard card access
- Automatic cash back on selected fuel purchases
- Real-time earnings and spending visibility in one app
- Early access to some earnings after completing eligible trips
- Built-in tools for separating business and personal expenses
Cons
- Availability and benefits vary by driver location
- Cash-back rates and eligible merchants can change
- Not designed as a full-service personal bank account
- Support may be slower for card-specific issues
- Requires qualifying Uber driver activity for some features
Uber Pro Card - Description
- App Name
- Uber Pro Card
- Package Name
- com.branchapp.uberprocard
- Developer
- Branch Messenger
- Category
- Finance
- Last Updated
- Jul 27, 2022
- Version
- 2026.8.3
I approached Uber Pro Card as a working driver would: not as another finance app to browse casually, but as a tool that needs to behave properly when earnings, transfers, and everyday spending are involved. Its purpose is closely tied to the Uber Pro Card experience, and the app is published by Branch Messenger. The central appeal is simple: it brings a driver-focused money workflow into one place instead of making you jump between an earnings screen, a separate card app, and a traditional bank account.
That focus is also the reason I would not recommend it automatically to everyone. If you drive with Uber and want a dedicated way to manage money connected with that work, it makes much more sense than a general budgeting app. If you are looking for a complete replacement for a normal bank, the narrower design may feel limiting. My experience with it is that the value comes from reducing steps around work income, while the main frustrations appear when account setup, identity checks, card access, or timing do not go as expected.
Where the experience usually gets stuck
The first important thing to understand is that this is a finance app, so a small setup problem can have a bigger effect than a minor glitch in a social or entertainment app. A driver may open it expecting to see a usable account immediately, then discover that the practical experience depends on completing the right registration path, entering matching personal details, and waiting for account or card-related actions to finish.
I found that the most confusing moments are often not inside the main screen itself. They happen around transitions: moving from the Uber environment into Branch Messenger’s service, confirming information, accessing the card, or expecting money to appear before the underlying transaction has completed. When something seems missing, it is tempting to keep tapping refresh. That rarely solves a verification or processing issue.
A useful habit is to identify exactly what has failed. There is a difference between being unable to sign in, seeing an account but not a balance, seeing a balance but not being able to use the card, and seeing an older transaction than expected. Each points to a different kind of problem. Treating all of them as “the app is broken” makes troubleshooting slower.
Another source of friction is expectation. The app’s store summary, “Keep more of what you earn,” communicates a goal rather than a promise that every payment becomes available instantly or that every banking task works like a full-service bank. I read it as a focused earnings and card-management tool. That distinction matters when deciding whether it fits your routine.
The listing shows a strong average of 4.9 from roughly 82 thousand ratings, which suggests that many users find the core workflow useful. I would still avoid treating that score as proof that setup will be effortless for every driver. Finance apps can work smoothly once an account is established while remaining frustrating for people whose information needs extra review or whose phone environment interferes with sign-in.
What to check before blaming the application
Before reinstalling, I would first check whether the phone is running a supported version of its operating system. The app requires at least iOS or Android version 10, so an older device can create problems that look like crashes, missing screens, or failed updates. I would also make sure the app itself is current; the listed version is 2026.8.3.
Next, I would confirm that I am using the same mobile number and personal details associated with the Uber Pro Card registration. Even a small mismatch can send a user into the wrong account path or make a verification step appear to stall. I would type information carefully rather than relying on an autofill entry that may use an old address, an abbreviated name, or a different phone number.
Connection quality deserves a separate check. A weak signal can affect sign-in, account loading, and actions that need a response from the service. I would try a stable Wi-Fi connection and then a reliable mobile connection, rather than repeatedly submitting the same request on an unstable network. If one screen loads while another remains blank, that often tells me the issue is communication with the service rather than the entire installation.
I would also check the phone’s date and time settings. Incorrect device time can interfere with secure sign-in and session validation. This is a small detail, but it is one of the practical checks people skip because the rest of the phone appears to work normally.
Finally, I would close other copies of the app, reopen it, and give a pending action time to settle before starting another one. In a money workflow, duplicate attempts are not a good troubleshooting strategy. A user should note what they pressed, what message appeared, and whether the balance or transaction history changed afterward.
A setup routine that avoids unnecessary loops
My preferred setup approach is deliberately slow. I would install the app from the official store, open it on a stable connection, and complete one stage at a time. I would keep the phone number and personal information consistent with the details already used for the Uber Pro Card. If the app asks for confirmation, I would finish that step before switching to another app or restarting the phone.
I would also avoid setting up the account while rushing between trips. A driver who is parked briefly may be tempted to begin registration, leave when a ride arrives, and return later without remembering which stage was completed. That can create confusion about whether the account was created, whether a confirmation was sent, or whether the next attempt is a new process. Completing setup in one calm session is more practical.
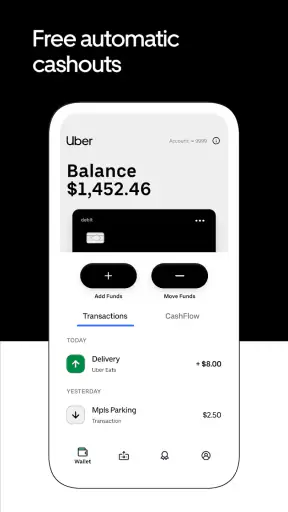
Once access is available, I would spend a few minutes learning the difference between the current balance, recent activity, and card-related controls. This is not wasted time. It gives me a reference point for later. If I know what a normal account screen looks like before my next work shift, I can recognize whether a later problem is a display issue, a delayed transaction, or a genuine access problem.
I would not judge the app only by how quickly the first screen appears. The more important test is whether I can reliably find the information I need after returning from a shift. For me, that means checking earnings-related activity, understanding what has already posted, and knowing where to look when a card action does not produce an immediate visible change.
The app is free, which removes one barrier to trying it, and it is rated for Everyone. That does not make setup risk-free, though. I would still treat it like a financial account: use a private device, protect sign-in details, and avoid handing the phone to someone else while the account is open. The age rating describes suitability, not a substitute for sensible account security.
Recovering a disrupted money workflow
When the app stops behaving normally, I prefer a recovery sequence that preserves information rather than wiping everything immediately. First, I capture the exact screen and message, without sharing sensitive account details publicly. Then I check the connection, close and reopen the app, and try the same action once. If the result is unchanged, I move to the account or service support route instead of repeating the action many times.
Reinstalling can be useful for a damaged local installation, but I would use it later in the process, not first. Removing an app does not resolve an account verification issue, a delayed transaction, or a service-side interruption. It can also force another sign-in, which is inconvenient when the original problem is that the user cannot complete authentication.
If a balance looks outdated, I would compare it with the activity shown in the app rather than assuming the number is permanently wrong. A transaction may need time to appear consistently across screens. I would avoid making a spending decision based only on a balance that seems surprising, especially if a recent transfer or card action is still being processed.
If the card is not working, I would separate card access from account access. Being able to open the app does not automatically mean that every card action has completed, and a card issue does not necessarily mean the whole account is unavailable. I would check the relevant status inside the app, confirm that I am looking at the correct card information, and record the time and circumstances of the failed attempt before contacting support.
There is also a useful recovery rule for drivers: keep a small buffer outside the work-linked card workflow. I would not make this app the only way to pay for fuel, food, or an urgent expense until I had used it long enough to understand how money moves through my own account. That is not a criticism of the product; it is sensible planning whenever income and spending depend on a digital financial service.
The app has passed the million-install mark, so it is clearly used at substantial scale. Even so, scale does not eliminate individual account problems. A broad user base can indicate that the main path is dependable while saying little about a particular phone, verification case, connection, or transaction state.
When the problem is outside the app
Some apparent failures belong to the surrounding system. If an Uber earnings event has not reached the relevant account flow, the card app cannot display information that has not arrived. If a card payment is declined at a merchant, the cause may involve the merchant terminal, network connectivity, card status, or account conditions rather than the app’s interface. The app is the place where the problem becomes visible, not necessarily where it began.
This is why I would avoid contacting support with only “it does not work.” A better report explains whether the issue concerns login, account creation, balance display, transaction visibility, or card use. I would include the device type, operating system version, approximate time, connection used, and the exact non-sensitive message. That gives the support team a clearer starting point without exposing private financial information.
I would also check whether the issue occurs everywhere or only in one location. If the app works on Wi-Fi but not mobile data, the phone’s network settings may be involved. If it works on one device but not another, the installation or device environment deserves attention. If the same action fails consistently across conditions, the account or service path becomes more likely than a simple local glitch.
Compared with a traditional bank app, the Uber Pro Card experience is more specialized. A bank usually offers broader services, such as multiple account types and a wider range of financial tools, while this app is more directly tied to the needs of drivers using the card connected with their work. Compared with a generic budgeting app, it is closer to an operational money tool than a planning dashboard. It helps make work-related money easier to access and monitor, but it is not the first choice for someone whose main goal is long-term budgeting, investment research, or managing several unrelated bank accounts.
That specialization is its strongest trade-off. A driver who wants a focused place for earnings and card activity may appreciate the reduced mental load. Someone who wants one app to organize an entire household’s finances may find themselves needing another service anyway. I would choose it for the former situation and avoid forcing it into the latter.
A realistic shift-by-shift use case
Imagine finishing a busy driving period and needing to check whether the money connected with that work is reflected in the account before paying for fuel and groceries. I would open the app, review the visible balance, and inspect recent activity instead of relying on memory. If the balance and activity do not line up with my expectation, I would pause and identify whether the issue is a delayed posting, an incomplete transfer, or simply that I am looking at the wrong section.
Later, before using the card for an important purchase, I would make sure the app opens normally and that I know how to reach the relevant card information. This small pre-check is more useful than discovering a sign-in problem at a checkout. I would also keep an alternative payment method available until I had confidence in the routine.
For a driver who works irregular hours, that workflow can be more useful than opening a general bank app and manually sorting work income afterward. The benefit is not flashy; it is the connection between the work context and the money-management task. The cost is that the app becomes less useful outside that context.
My practical verdict for drivers
After using it with that perspective, I see Uber Pro Card as a focused finance app rather than a universal banking replacement. Branch Messenger has built the experience around a specific audience, and the free entry point makes it easy for eligible users to evaluate whether the workflow suits them. The current version, 2026.8.3, also means users should keep the installation updated rather than relying on an old build when troubleshooting.
The real strength is concentration: work-related money and card activity are easier to approach when they live in a purpose-built workflow. I especially like the idea of checking activity after a shift, separating posted information from expectations, and using the app as a practical checkpoint before spending. Those habits make the tool more dependable than simply opening it only when something has gone wrong.
My reservations are equally practical. Setup and verification can be more sensitive than with an ordinary utility app, and a delayed transaction can be difficult to interpret if you expect every change to appear immediately. The app also will not replace the broader planning features of a full bank or budgeting service. Drivers should keep that boundary in mind and maintain a backup payment option until they understand their own routine.
I would recommend it to an Uber driver who wants a dedicated way to handle money associated with driving and is comfortable following a careful setup process. I would suggest skipping it if you do not use that work ecosystem, need extensive household-finance tools, or prefer to keep all money in an established bank relationship. In those cases, a conventional bank app or a budgeting tool may be a better center of gravity.
Overall, my opinion is positive but conditional. The app is most convincing when used for its actual job: checking and managing the card-linked side of work earnings without adding unnecessary steps. If you approach setup patiently, distinguish account issues from phone or network issues, and keep a backup payment method during the learning period, it can become a useful part of a driver’s routine rather than another app that creates uncertainty at the worst moment.
FAQ
What is the Uber Pro Card, and who can use it?
The Uber Pro Card is a financial account and debit card designed for eligible Uber drivers and delivery couriers. It can be used to receive earnings, make purchases, withdraw cash, and manage money through the companion app. Availability, eligibility, and specific features may vary by country, region, and whether you drive with Uber, deliver with Uber Eats, or meet certain activity requirements.
How do payments and instant payouts work with Uber Pro Card?
After setting up the account, eligible earnings can generally be deposited directly to the Uber Pro Card account. Depending on the market and account terms, users may receive automatic payouts after completing trips or deliveries, while other funds may follow a regular schedule. Processing times, limits, and any applicable fees should be checked in the app before relying on the card for urgent expenses.
Are there fees for using the Uber Pro Card?
The Uber Pro Card may offer features such as no-fee access to certain earnings or participating ATMs, but fees can still apply in specific situations. Possible charges may involve out-of-network ATM withdrawals, card replacement, international transactions, or other optional services. Because terms differ by location and can change, review the current fee schedule shown during registration and in the app.
Can I use the Uber Pro Card for everyday purchases and cash withdrawals?
Yes, the card is generally intended for everyday spending wherever the supported debit-card network is accepted. You may also be able to withdraw cash at eligible ATMs, subject to transaction limits and network availability. Before downloading or activating it, check whether your preferred merchants, ATM locations, digital-wallet services, and cash withdrawal options are supported in your country.
Is the Uber Pro Card safe, and what should I do if my card is lost?
The app typically includes account controls that help users monitor transactions, manage the card, and respond to suspicious activity. If the physical card is lost or stolen, freeze or lock it through the app as soon as possible and contact support using the official help channels. Never share your password, verification codes, PIN, or full card details with anyone claiming to represent Uber.


